Future-Proofing Tips from Greenhouse Growers That Recovered from Natural Disasters
 September 3, 2025
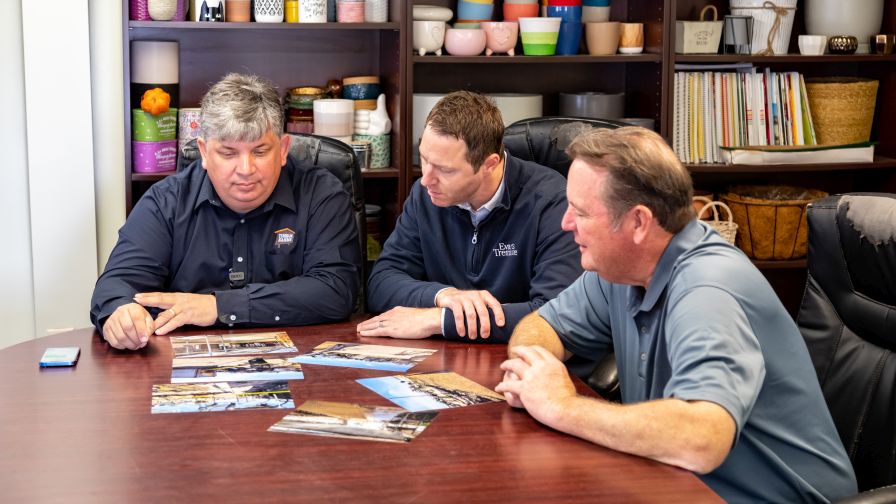
(L to R) Jim Gibson (Owner of Timbuk Farms), Todd Mazur (local insurance agent), and Tom Richey (Hortica Claims Manager) discussing their claim. | Hortica and Timbuk Farms
As many as 90% of businesses fail within two years after being struck by a disaster, according to the U.S. Small Business Administration. Greenhouse owners face significant weather-related risks that vary by geography. From wildfires to earthquakes, tornadoes, and flash floods, weather-related risks are becoming more common and damaging due to ongoing climate change — and your best bet is to implement proven steps to help protect your business.
In 2022, Timbuk Farms in central Ohio suffered a devastating spring fire that destroyed the company’s greenhouses, spring crops, and offices. Owner Jim Gibson said the damage spanned the length of a football field.
Recovery is never easy because of the real emotional, operational, and financial strains. But with the lessons learned from Timbuk Farms and other greenhouses that have recovered after a disaster, you can help your employees and business recognize the value of planning, practicing, and revising business continuity and emergency plans, and the importance of understanding your insurance coverages and the claims process.
Common Challenges Businesses Face During Disaster Recovery
In a handful of hours in the middle of the night, Timbuk Farms faced sudden structural damage to buildings, lost crops, ruined equipment, and questions about how to resume operations as quickly as possible. The company faced some of the most common disaster recovery challenges, including:
Operational Disruptions
Disasters can halt operations overnight, as a fire did to Timbuk Farms. Whether it’s a damaged greenhouse, flooded fields, or equipment failure, even a short disruption can throw off or halt seasonal production, cause missed deliveries, and sink retail operations.


Financial Strains
The financial impact of disasters on businesses can be immediate and severe, especially if your insurance coverage isn’t up to date. Inflation, labor shortages, and supply chain delays make repairs more expensive and time-consuming than anticipated. Additionally, extended timeframes for securing building permits are becoming increasingly common as local governments reconsider their building requirements in light of ongoing climate change.
Emotional Tolls
The pressure to protect employees, restore operations, and preserve customer relationships can take a heavy toll on owners and staff. Losing a crop is bad, and losing future crops and customers compounds difficulties. Pressures increase when employees are forced to find alternative work because their wages aren’t covered during recovery.
Key Lessons Learned from Greenhouse Businesses That Recovered
Businesses that bounce back from catastrophe — like Timbuk Farms — often share common themes in how they prepare, respond, and rebuild. Here are important prevention and recovery lessons for businesses from greenhouse operators who’ve successfully recovered:
Manage Risks Starting at the Top
Every effective disaster recovery plan begins with leadership. Leaders must communicate the value of a strong safety culture, model best practices, and ensure preparedness is a companywide priority — not an afterthought.
Regularly Review and Update Your Plans
Risk management, emergency response, and business continuity plans that sit in a drawer won’t help in a crisis. Revisit, update, and revise your plan regularly — at least annually and especially after busy seasons — to identify changes such as new equipment or buildings, or increases to stocked items. Identify gaps, consider new risks, and ensure that key personnel are trained and ready. Talk with your insurance provider, who may have risk management resources to support this work.
Think Beyond Your Property Lines
Greenhouse operators often plan for weather-related damage on-site, but the risk extends far beyond the facility. What if a delivery truck crashes or a key associate has a health emergency while off-site? Your business continuity plan should also consider these scenarios.
Evaluate Insurance Adequacy Before It’s Too Late
Update property valuations regularly and consider business interruption coverage for up to 24 months. With rising construction and material costs, and increasing delays for building permits, many businesses are unknowingly exposed.
Build a Resilient Team and Partner Network
Recovery is not a solo effort. Identify key internal leaders and establish relationships with external experts — including insurers, legal counsel, and suppliers — before disaster strikes.
For information on navigating greenhouse damage claims, you can read the full article on GreenhouseGrower.com, our sister brand.